

Kevin Dick
Posted on Sep. 25, 2026
In January 2026, my wife and I welcomed our first child, a baby boy. The months leading up to his arrival were full of milestones: surprising our parents, finding out the gender, picking out a name, setting up the nursery — the list goes on. Then the day finally came when we got to hold him in our arms. It’s cliché, but once you become a parent something instinctive switches on. Parenthood changes your outlook on life.
Now, as a financial advisor, the cost of raising a child was in the back of my mind the whole time (sometimes my profession is a curse). We all want what’s best for our kids, and whether we like it or not, money and children go hand in hand. That’s why a solid financial foundation matters so much; it shapes the environment your children grow up in.
I know the financial implications of becoming a parent in the year 2026 firsthand. Between expensive baby supplies, daycare, student loans, and buying our first home, I’m “in the trenches” so-to-speak. So, when I first heard about Trump Accounts a little over a year ago, I was intrigued. Free money for my child? Who wouldn’t be? But government programs don’t always come to fruition, and even if they do, the rollout doesn’t always meet expectations. So, before advising clients on Trump Accounts, I wanted to go through the process myself. To that end, this article is meant to give other parents an inside look into opening, funding, and maintaining one of these custodial investment accounts.
What Is a Trump Account?
In July 2025, the federal government established a new, federally sponsored investment account for children called the “Trump Account.” For all intents and purposes, it’s a retirement account for kids. When a Trump Account is first opened, the federal government immediately contributes $1,000 for children who meet certain criteria. From there, the money generally grows tax-deferred until the child turns 18 and takes ownership of the account.
The initial $1,000 government deposit goes to U.S. citizens born between January 1, 2025, and December 31, 2028. Children born before 2025 who are age 10 or younger may still be eligible to receive a separate $250 private donation. However, any U.S. citizen under age 18, regardless of circumstance, can open a Trump Account even if they don’t qualify for either deposit. This is a common misconception among parents whose children were born before 2025. Even without seed money, it may be worth opening an account for the tax advantages alone.
Accounts can receive up to $5,000 in contributions per year. That limit will be indexed to inflation starting after 2027, so it will increase slightly each year as the cost of living goes up. Employers can also contribute up to $2,500 a year to an employee’s child’s Trump Account and take a tax deduction, so it’s worth exploring whether this is offered at your workplace. However, it’s important to note that employer contributions still count towards the $5,000 annual limit.
For the finer details, visit our Trump Account 101 FAQ page.
Activating the Account
The official Trump Account site (www.trumpaccounts.gov) will direct you to download the mobile app, either with a QR code or through an app store link.
Before the account can be activated, you need to complete IRS Form 4547. You can file it with your tax return, but most parents will probably create an IRS account through ID.me and complete the form that way (that’s how I did it). It sounds complicated, but it isn’t. Once you open the app, it walks you through a workflow I found easy to follow. Just make sure you have your child’s Social Security number and other personal information readily available.
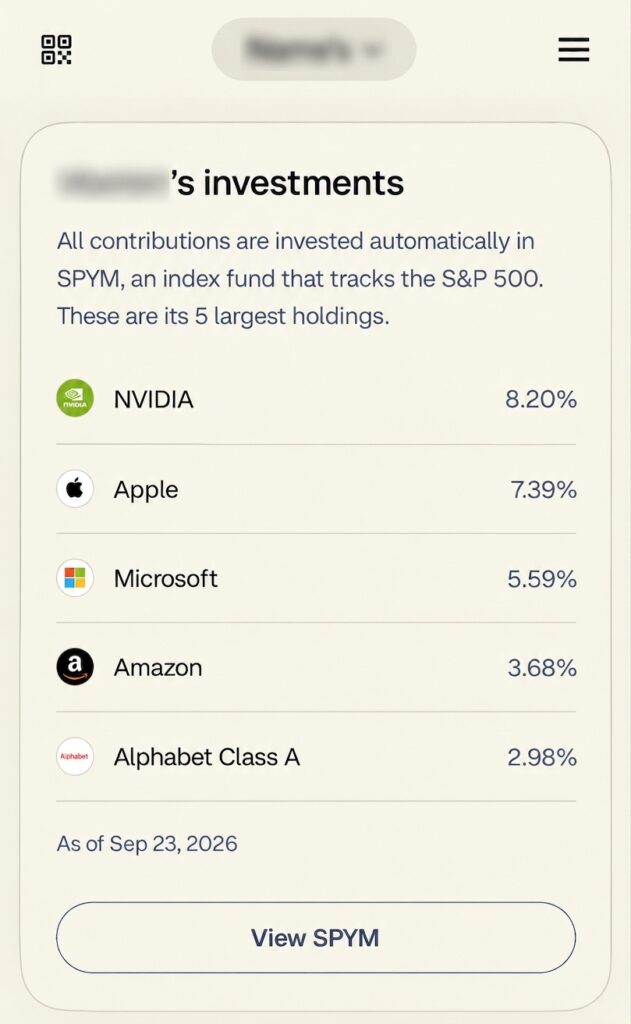
Once the account is open, you manage it through the app. However, parents can’t choose the investments. Currently, all funds are automatically invested in SPYM, a low-cost ETF that tracks the S&P 500.
The Mobile App Experience
In my years working with legacy brokerage apps, I’ve found most of them a bit clunky. To be fair, many brokerage firms predate smartphones, the internet, and even computers, so they’ve been building the plane while flying it. Nevertheless, building an investment app from scratch in the 2020’s is a big advantage because you already know what consumers want and what technology you need to deliver it. The Treasury Department also smartly partnered with a firm called Robinhood, a fairly new company (by financial industry standards) which is at the forefront of financial app design. The result is a mobile app that is very well-executed, in my opinion.
That said, there isn’t much to do once you’re in the app — which is probably by design. The user experience is clearly built around simplicity and transparency. Visual learners will appreciate the main dashboard, which features a large graph of your child’s balance, along with the total dollar amount and investment returns displayed prominently at the top. The dashboard is also highly interactive. For example, you can view a hypothetical account balance at ages 18 and 60 based on different monthly contribution amounts (although, I’d advise against looking at what year your child turns 60… woof). Scroll down and you’ll find another interactive chart showcasing exactly which companies your child is invested in, and how much of each.
If you have more than one child with a Trump Account, a dropdown at the top of the dashboard lets you to toggle between accounts instantly. The “hamburger” menu in the top right corner holds the account management options you’d expect from most financial portals, ranging from “Account Statements” and “Recurring Contributions” to “Settings” and “Notifications.” You can also have monthly statements emailed to you directly, which I found helpful.
Overall, I’m pleasantly surprised with the Trump Account user experience.
Contributing and Receiving Gifts
As a Parent or Guardian:
From a financial advisor’s perspective, the contribution page is probably my favorite part of the app. To find it, tap the middle of the three tabs at the bottom of the dashboard (the piggy bank icon).
Remember the $5,000 annual limit? Normally, going over a contribution limit by accident is a major headache that can lead to tax problems. It happens more often than you’d think, especially to investors doing it on their own. However, Trump Accounts avoid all that because the app has built-in safeguards that prevent you from exceeding the limit. When you go to contribute, the app shows how much money has already been deposited this year, who deposited what, and, most importantly, how much room is left for more contributions. The remaining limit even updates in real time as you type the amount you’d like to contribute.
Once you’ve entered your payment information, it’s saved for future deposits.

From Friends and Loved Ones:
In the top left corner of the dashboard is a small icon that resembles a mini QR code. Tap it and you’ll see a larger QR code along with a “share link” button, providing you with two ways to invite family and friends to contribute to your child’s Trump Account.
The QR code works like the ones in mobile payment apps such as Venmo and Cash App. When someone scans it with their phone, it takes them to your child’s contribution page. From there, it’s pretty self-explanatory: the contributor enters an amount, their name, and a short message for your child before providing their payment information [1]. This is ideal for spur-of-the-moment gifts, like when you’re out to dinner with your folks or at a holiday party and someone wants to give your child something.
The share link works the same way, except you text or email the link instead of having someone scan the code in person. The contribution process from there is basically identical. Also, just like with parent contributions, the app shows the remaining limit and keeps friends and family from accidentally going over it.

[1] Gifts and contributions to Trump Accounts cannot be made using a credit card. They can only come from a bank account or debit card, and that includes contributions from parents. Some of my family members ran into trouble contributing to my son’s account because they entered credit card information instead of debit card information.
My Takeaway
There’s a growing debate over whether it makes more sense to fund a Trump Account or another tax-advantaged investment account like a 529 plan. Neither is perfect. The biggest drawback of Trump Accounts is access. Once your child turns 18, the account follows traditional IRA rules, so most withdrawals before age 59 ½ trigger income taxes and an additional 10% penalty. 529s come with their own strings attached. Withdrawals for anything other than qualified education expenses face taxes and penalties on the earnings. That said, 529s have become more flexible in recent years, where unused funds can now be rolled into a Roth IRA for the beneficiary, within limits.
For many families, the answer isn’t either/or. A 529 can cover nearer-term goals like college, while a Trump Account will compound over decades toward retirement or even a first-home purchase. What I can say is that I’ve never had a client tell me they regretted putting money away for their child. When you approach it thoughtfully, it’s hard to go wrong investing in your children’s future.
We’re still in the early innings of the Trump Account program, and it will likely evolve over time. But if your child qualifies for a seed deposit, it’s worth claiming that money while it’s available. How a Trump Account fits alongside a 529 plan, custodial accounts, or your own retirement savings, however, should be part of a much broader financial conversation.
This content is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. Investing involves the risk of loss, including the possible loss of principal. You should consult your own advisers as to legal, business, tax, and other related matters concerning any investment.